Denied Storm Claim Lawsuits Surge as Texas Deadlines Expire
A Florida jury recently turned one couple's $46,000 denied hurricane claim into a verdict worth more than $400,000 — but for Texas homeowners with 2024 and 2025 denied storm claims, the statute-of-limitation window to sue is closing right now.
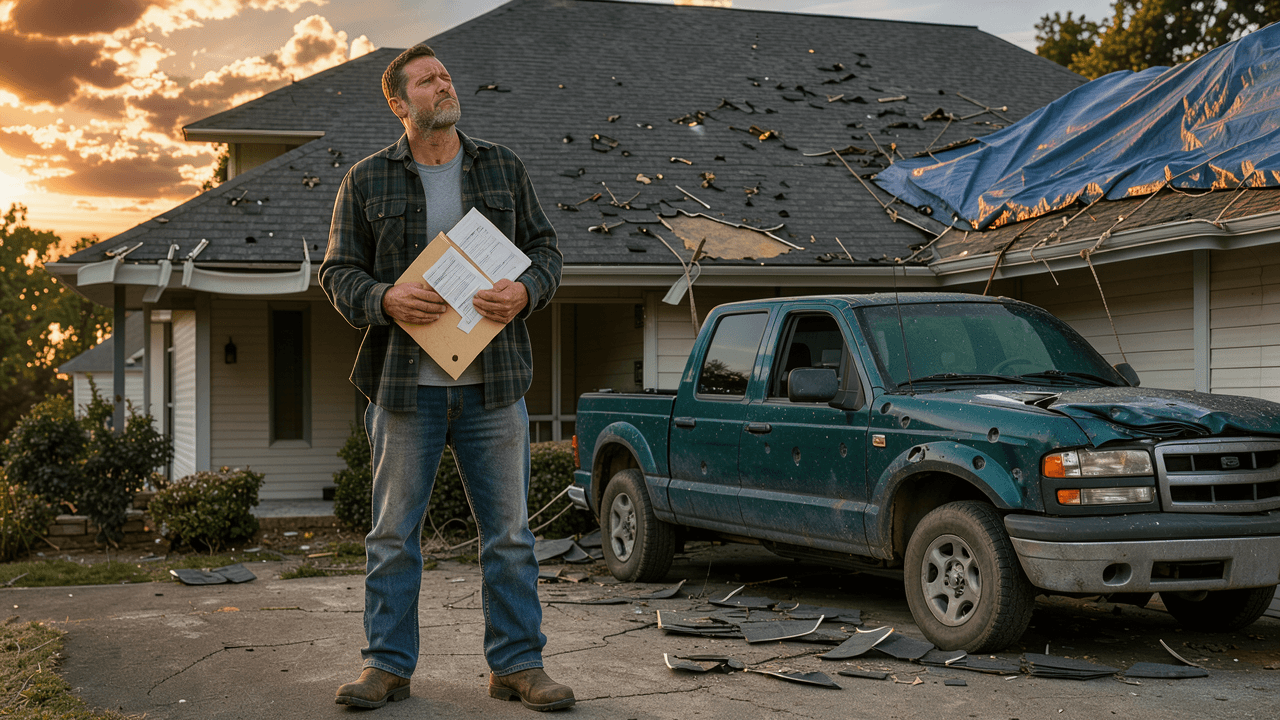
Why Denied Storm Claim Lawsuits Are Surging in Texas Right Now
If your hail, wind, or water damage claim was denied in 2024 or 2025, the clock may be closer to running out than you realize. Legal analysts at JD Supra warned on October 16, 2026 that Texas property owners with denied 2024 and 2025 storm claims are approaching statute-of-limitation deadlines — and once those dates pass, homeowners lose all legal recourse. The result is a surge of last-minute demand letters and claim re-evaluations across the state.
There's a second reason for hope in the headlines this week. As reported by Moneywise and Yahoo Finance on October 17–18, 2026, a Florida couple whose $46,000 Hurricane Ian claim was denied by Citizens Insurance took the carrier all the way to trial — and the verdict could top $400,000. Nearly two years of legal headaches, yes, but the reporters' takeaway is the one that matters to you: a denied claim is not necessarily the final word.
Here's the practical translation. If your storm claim was denied, you are not powerless — but you do need to move deliberately and quickly. The steps below will help you preserve your rights, strengthen your file, and protect your home while a denied storm claim lawsuit remains an option.
- Locate your denial letter and policy today. Your deadline math starts with these two documents.
- Do not delete anything. Photos, emails, estimate PDFs, and texts with your adjuster are all evidence.
- Prevent further damage now. Unresolved roof or water issues get worse — and can complicate your claim.
- Calendar a "call an attorney" date within the next two weeks, not the next two months.
Step One: Read the Denial Letter the Way an Attorney Would
A report from KQ2 on October 15, 2026 summed up the problem many homeowners face: after a severe storm, you're dealing with physical damage and a complex administrative process at the same time. That complexity is exactly where denials are born. Most denied storm claims fall into a handful of predictable categories, and each one calls for a different response:
- "Excluded peril" denials — the insurer says the damage came from excluded wear and tear, flood rather than wind-driven water, or pre-existing conditions. These often hinge on causation and are frequently contestable with independent inspections and weather data.
- "Insufficient documentation" denials — the insurer couldn't verify the scope of damage. This is the most fixable category, and the one where a second estimate and better photo evidence can change everything.
- "Late notice" denials — the claim was reported long after the storm. If you reported promptly and can prove it, gather that proof immediately.
- Lowball payments framed as denials — the insurer paid a small amount while rejecting the real scope of loss. In practice, many of these become denied storm claim lawsuit candidates once independent estimates reveal the gap.
Whatever the stated reason, put your requests in writing. Ask the insurer for the complete claim file, including the adjuster's report, photos taken at the inspection, and the exact policy provisions cited in the denial. Insurers are required to explain denials, and a vague or shifting explanation is itself useful information if your case proceeds.
Know Your Deadline Before You Plan Anything Else
This is the issue driving the current surge. Many Texas homeowner policies contain a clause — often titled "Suit Against Us" — requiring legal action within roughly two years of the date of loss or the denial. That is why claims from 2024 are expiring now and why 2025 claims are next in line, as the JD Supra analysis highlighted. Separate provisions under Texas insurance law, including prompt-payment and bad-faith protections, carry their own timelines, so you should never rely on a single date or on advice from a neighbor.
Protect yourself with these steps:
- Find the suit-limitation language in your policy and highlight the exact period and trigger date it references.
- Write down your key dates — the storm date, the claim date, the inspection date, and the denial date — and keep them with your file.
- Consult a Texas insurance attorney promptly to confirm your precise deadline. Do not try to calculate it yourself; courts and policies interpret these clauses differently, and a miscalculation can be fatal to your claim.
- Understand what a demand letter does. As the current wave of filings shows, many insurers re-evaluate a claim when they receive a well-documented demand letter from an attorney or public adjuster — sometimes resolving it without full litigation. But a demand letter is not a filing. If litigation is needed, the lawsuit itself must be filed by your deadline.
The homeowners who lose their rights are rarely the ones who were told "no." They're the ones who waited until the deadline had already passed to ask what their options were.
Build the Evidence File a Denied Storm Claim Lawsuit Actually Needs
Whether your case ends in a settlement negotiation, a re-evaluation, or a full trial like the Florida Citizens case, one thing is constant: the side with the better documentation usually wins. Start assembling your file now, even if you haven't decided whether to pursue legal action. The stronger your file, the more leverage you have at every stage.
- Dated photos and video of all damage — roof, siding, windows, ceilings, floors, attic, and contents. Wide shots and close-ups, plus anything from before the storm if you have it.
- Two or more independent repair estimates from licensed contractors, ideally itemized by line item so they can be compared against the insurer's scope.
- Receipts for every emergency repair and temporary measure — tarping, board-up, water extraction, drying equipment, hotel stays, and meals if you were displaced. These are typically recoverable, and paper copies matter.
- Weather records for your address on the date of loss — hail reports, wind speeds, and storm tracking data that tie your damage to a covered event.
- A correspondence log — every call, email, and letter with your insurer, with dates and names. Gaps and delays in the insurer's handling can matter later.
- Your proof-of-loss, estimate worksheets, and the full claim file you requested in writing.
If water entered the home, document moisture issues carefully, because storm damage and its aftermath often overlap. Our water damage guide explains extraction, drying, and documentation standards, and our mold remediation guide covers what to do if damp conditions have already lingered for more than a day or two. Mold that develops from an unresolved storm leak is frequently part of the same claim — but only if you can show you mitigated promptly.
Protect Your Home While You Fight the Denial
Almost every policy requires you to mitigate damage — take reasonable steps to keep it from getting worse. This duty doesn't pause while your claim is disputed, and insurers sometimes use delayed repairs as a reason to reduce later payments. Practically, that means:
- Tarp or repair the roof temporarily and keep the receipts and before/after photos.
- Dry out wet materials within 24–48 hours whenever possible; standing water and damp drywall escalate quickly into structural and mold problems.
- Keep temporary repairs truly temporary. Don't begin permanent reconstruction until you understand whether the insurer wants to re-inspect — destroying the evidence of damage can weaken your case.
- Document conditions continuously — a short dated video walkthrough each week costs nothing and can prove a great deal.
Cooperation and documentation are not the same as acceptance. You can mitigate responsibly, provide requested records, and still pursue a denied storm claim lawsuit on the original denial if talks fail.
When "No" Looks Like Bad Faith
A October 20, 2026 piece in the El Paso Times made a point worth underlining: the adjuster says no — but a denial isn't always the end, and some denials cross into bad-faith territory that Texas law addresses directly. You don't need to become a legal expert. You just need to recognize the warning signs that justify a professional second opinion:
- A denial issued without a real inspection, or based on an inspection that missed obvious damage.
- Unexplained delays, missed adjuster appointments, or requests for the same documents repeatedly.
- An estimate far below every independent quote you've obtained, with no itemized explanation.
- Pressure to accept a quick, final settlement before you've completed repairs or understood your deadline.
- A denial that cited one policy provision, then a different one when you asked follow-up questions.
If any of these sound familiar, say so explicitly when you consult an attorney or a public adjuster. Bad-faith issues can broaden the remedies available to you — but only if they're raised within the applicable time frames.
Lessons From the $46,000 Claim That Turned Into $400,000
The Florida Citizens trial that made headlines this week offers three takeaways for Texas homeowners staring at a denial letter. First, persistence pays: the couple refused to treat a $46,000 denial as the last word, and the eventual outcome reportedly exceeded $400,000. Second, time cuts both ways — the process took nearly two years of legal headaches, which is precisely why acting early, while your documentation is fresh and deadlines are distant, gives you the best position. Third, professional distance matters: an independent inspection and independent estimates gave the homeowners a factual foundation the insurer couldn't ignore.
Your case will not mirror theirs, and no outcome is guaranteed. But the core playbook is the same for any homeowner: verify the deadline, build the file, mitigate the damage, and get qualified professionals involved before options expire.
Frequently Asked Questions
How long do I have to file a denied storm claim lawsuit in Texas?
It depends on your policy and your specific facts. Many Texas homeowner policies include a suit-limitation clause of roughly two years from the date of loss or denial, which is why 2024 claims are expiring now, as the recent JD Supra analysis reported. Locate the "Suit Against Us" clause in your policy, write down your key dates, and confirm your exact deadline with a Texas insurance attorney as soon as possible — never assume you have more time than you do.
Is a denial letter final? Can I really still recover money?
No — a denial is an insurer's position, not a court's judgment. The $46,000 Hurricane Ian claim denied by Citizens and taken to trial in 2026, with reported outcomes topping $400,000, is the clearest recent illustration. Many denied claims are resolved through demand letters, re-evaluations, or settlement negotiations before trial, provided the evidence file is strong and the deadline hasn't passed.
Do I need an attorney, a public adjuster, or both?
They do different jobs. A public adjuster re-evaluates the damage and rebuilds the scope and pricing of your claim; an attorney protects your legal rights, manages deadlines, and can file suit or assert bad-faith claims. Many homeowners with significant damage use both, with the adjuster strengthening the numbers and the attorney handling the legal process. Either way, act while your deadline still allows both paths.
I already made repairs. Did I ruin my case?
Not necessarily, but documentation becomes even more important. Gather everything you have: pre-repair photos or videos, contractor invoices, material receipts, inspection reports, and any insurer correspondence. If you haven't started permanent repairs yet, hold off until you've confirmed whether the insurer or your attorney needs to re-inspect, and keep any temporary repairs documented and modest.
Will filing suit hurt my relationship with my insurer or raise my premiums?
Insurers cannot lawfully retaliate against you for pursuing the benefits you paid for, and re-evaluations following a demand letter are routine — the current surge in Texas is proof of that. What genuinely harms homeowners is missing a filing deadline or accepting a lowball settlement under pressure. Focus on your documentation and your dates, and let your attorney manage the strategy.
Get a Second Opinion Before Your Window Closes
If your 2024 or 2025 storm claim was denied, the most expensive thing you can do is nothing. Start by confirming your deadline, then strengthen your position with a well-documented, professionally scoped claim. At restorationcompanion.com, we help homeowners navigate exactly this moment — from emergency mitigation and moisture control to damage documentation that stands up to re-inspection. Download our free Quick Claim Checklist to make sure your file contains everything adjusters, public adjusters, and attorneys will ask for, browse our water damage and mold remediation guides for storm-specific restoration steps, and contact our team today for a claim review and connection to vetted restoration professionals in your area. Denials are re-opened every week — but only for homeowners who act before the deadline does.